THE BLUESKYVIEW
Evidence. Impact. Better Decisions.
Is Your CSR Disaster-Relief Programme Creating Recovery?
₹2,117.85 crore released to flood-hit States under the SDRF. NDRF teams pre-deployed across seven States through the 2026 monsoon. Rainfall forecast at 90% of the long-period average.
India’s disaster-response machinery moves fast once floods strike. But for corporates investing in disaster-relief and rehabilitation programmes, there is a question that goes beyond whether the spend qualifies under Schedule VII of the Companies Act, 2013:
What changed after the relief was delivered?
- Relief kits distributed are an output.
- Funds disbursed to affected States are an output.
- Communities that recover, rebuild livelihoods and become more resilient to the next disaster are closer to an outcome.
And this is where CSR impact assessment becomes important.
India’s disaster-response conversation is changing. The scale of this year’s response is increasingly visible.
- As of August 2026, the Union Home Minister approved advance release of more than ₹2,117.85 crore in SDRF assistance to seven flood-affected States, with National Disaster Response Force teams pre-deployed and logistical support extended by the Ministry of Defence.
- Separately, the India Meteorological Department revised its 2026 southwest monsoon forecast to 90% of the long-period average, placing the season in the “below normal” category — the first such downgraded forecast in over a decade.
These developments point to an important shift: disaster response is increasingly being recognised not simply as a one-time relief exercise, but as a question of preparedness, recovery and long-term resilience.
For companies, that creates an opportunity—but also a measurement challenge.
Does disaster relief qualify under Schedule VII of the Companies Act, 2013?
Disaster-relief interventions fall within Item (xii) of Schedule VII of the Companies Act, 2013, inserted by the Companies (CSR Policy) Amendment Rules, 2021, which covers disaster management, including relief, rehabilitation and reconstruction activities. But there is an important qualification that CSR teams should not overlook.
Contributions must be routed through eligible implementing mechanisms and reported in the prescribed format under the CSR Rules, and relief distributed directly to affected individuals needs a proper documentation trail—board approval, beneficiary records and utilisation certificates—to be counted as CSR expenditure rather than ordinary philanthropy.
This matters when a company describes a disaster-response contribution as a CSR programme without that supporting trail in place.
What difference is your CSR initiative making?
Most programmes begin their measurement journey by asking:
“How much did we distribute?”
We believe the better question is:
“What did our intervention enable communities to recover from?”
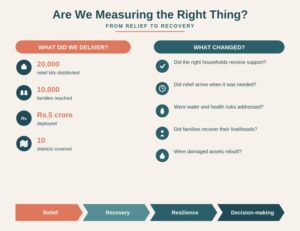
These are useful programme metrics.
The further we move along this chain, the more meaningful—and more demanding—the evidence needs to become.
- Distribution records tell us who received support.
- Beneficiary feedback tells us whether support was relevant.
- Recovery assessments tell us whether households actually moved towards stability.
- Longer-term outcome evaluation can help us understand whether vulnerability was reduced.
Relief becomes recovery. Recovery becomes resilience. And resilience becomes the real measure of impact.
Five Questions a Good CSR Disaster-Relief Programme should answer:
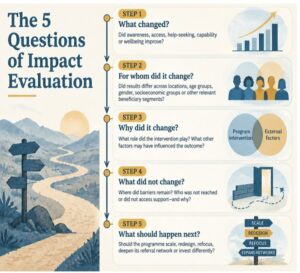
Sometimes the most valuable finding is not that relief reached thousands of people. It is discovering which needs persisted after the emergency, which communities remained vulnerable, and what should be done differently next time. Impact assessment creates value when it makes these differences visible—and helps decision-makers act on them.
A strong assessment should therefore be capable of producing uncomfortable findings as well as positive ones.
- If relief was delivered on time but recovery support did not follow, that is important.
- If some households recovered but others remained vulnerable, that is important.
- If a programme reached accessible areas but not the hardest-hit communities, that is important.
At BlueSkyCSR, this is the lens we bring to the impact assessment of CSR projects. We look beyond relief distribution to examine implementation, beneficiary experiences, recovery, outcomes and longer-term impact. Talk to BlueSkyCSR about designing an assessment around the decisions your evidence needs to inform.
Sources
- Ministry of Home Affairs, Government of India. Union Home Minister and Minister of Cooperation Shri Amit Shah approves advance release of ₹2,117.85 crore to flood-affected States under SDRF, 1 August 2026 (PIB).
- India Meteorological Department, Ministry of Earth Sciences, Government of India. Updated Long Range Forecast for the Southwest Monsoon Seasonal Rainfall, 2026, 29 May 2026.
- Ministry of Corporate Affairs, Government of India. Companies Act, 2013 — Section 135 and Schedule VII, Item (xii), inserted by the Companies (CSR Policy) Amendment Rules, 2021, covering disaster management, including relief, rehabilitation and reconstruction activities.
- Ministry of Corporate Affairs, Government of India. FAQ on Corporate Social Responsibility, including documentation requirements for CSR expenditure.